
Small Business Owners Could Be a Bigger Market for Mortgage Brokers
Some potential clients aren’t calling because they don’t think they can qualify for a mortgage.
Newrez recently surveyed 99 mortgage loan originators, 96 of whom said they work with small business owners who use business income to qualify for a mortgage. Unless otherwise noted, the survey percentages in this article are based on responses from those 96 originators.
84% of those 96 originators said many of those clients could qualify sooner than they realize. These originators reported that small business owners represented a median of 25% of loan volume, with four in ten saying the share was even higher.
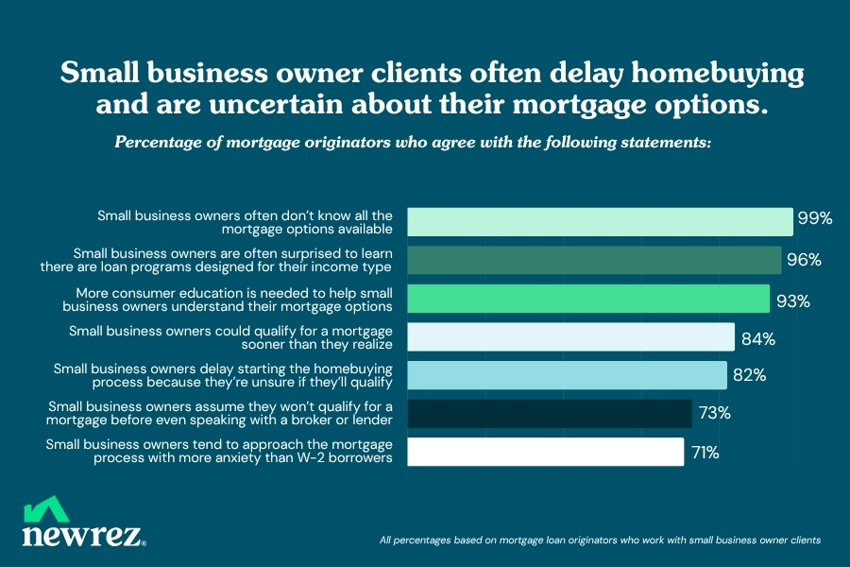
That means some prospective borrowers might not even be reaching out. Among the 96 originators who work with these borrowers, 73% said their small business owner clients assume they won’t qualify for a mortgage before even speaking with a broker or lender, while 82% said these clients delay starting the homebuying process because they’re unsure whether they’ll qualify.
Click to navigate:
- For Some Brokers, Small Business Owners Already Account for Significant Loan Volume
- Awareness Can Be as Big a Barrier as Qualification
- Tax Write-Offs Are the Most Common Qualification Challenge
- Small Business Owners Are Using Both Conventional and Non-QM Loans
- Interest-Only Financing Can Help with Cash-Flow Needs
- Start the Conversation Earlier
For Some Brokers, Small Business Owners Already Account for Significant Loan Volume
Small business owners aren't a niche segment for the mortgage originators Newrez surveyed.
Among the 96 respondents who work with small business owners using business income to qualify:
- 35% said these clients account for 26% to 50% of their loan volume.
- The median share of loan volume was 25%.
Small business owners come to the mortgage process at different points, and originators who work with them see both first-time and repeat buyers:
- 16% of originators said their small business owner clients are primarily first-time buyers.
- 55% said their small business owner clients are split about evenly between first-time and repeat buyers.
- 29% said their small business owner clients are primarily repeat buyers.
When respondents that work with small business owners who selected “about even” are counted in both categories, 71% said at least half of these clients are first-time buyers, while 84% said at least half are repeat buyers.
Awareness Can Be as Big a Barrier as Qualification
Seventy-five percent of respondents who work with small business owners said lack of awareness about mortgage options is at least as big an obstacle for their clients as financial qualifications. This includes 65% who said the two are equally significant and another 10% who said awareness is the bigger problem. Only 25% pointed to financial qualifications alone.
The same concern appeared elsewhere in the survey: 93% agreed that more consumer education is needed to help small business owners learn about available mortgage options.
Tax Write-Offs Are the Most Common Qualification Challenge
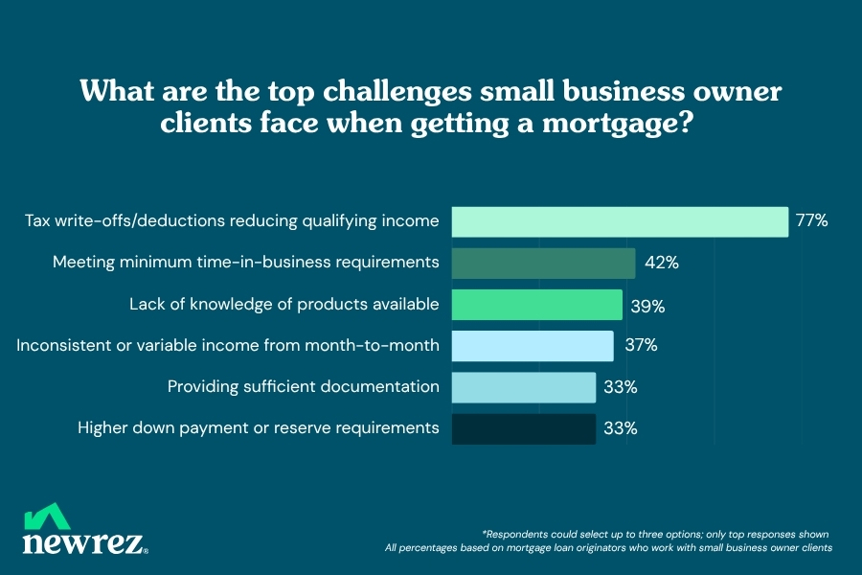
Seventy-seven percent of originators who work with small business owners said write-offs that shrink qualifying income are a challenge for these clients. The same deductions that lower a borrower’s tax bill also lower the income a lender can count when evaluating the borrower for a conventional loan. Other mortgage options may allow eligible borrowers to qualify using different forms of income documentation.
Before pitching a particular loan, brokers should establish how the borrower earns money, how that income appears on tax returns and what supporting documentation is available.
Small Business Owners Are Using Both Conventional and Non-QM Loans
Forty-seven percent of surveyed originators who work with small business owners said these clients are about evenly split between conventional and non-QM loans. Another 28% said these borrowers mostly use non-QM loans, while 25% said they mostly use conventional financing.
Non-QM options may help address some of the qualification challenges these originators identified. For eligible borrowers whose tax returns don’t fully reflect their income because of business write-offs, SmartSelf, part of the Newrez Non-QM Smart Series, may allow them to qualify using bank statements, 1099s or a profit-and-loss statement. Interest-only financing may also be worth discussing with small business owners with inconsistent or seasonal income. Lower required payments during the interest-only period can help during slower periods, while borrowers can choose to put more toward their mortgage when business picks up.
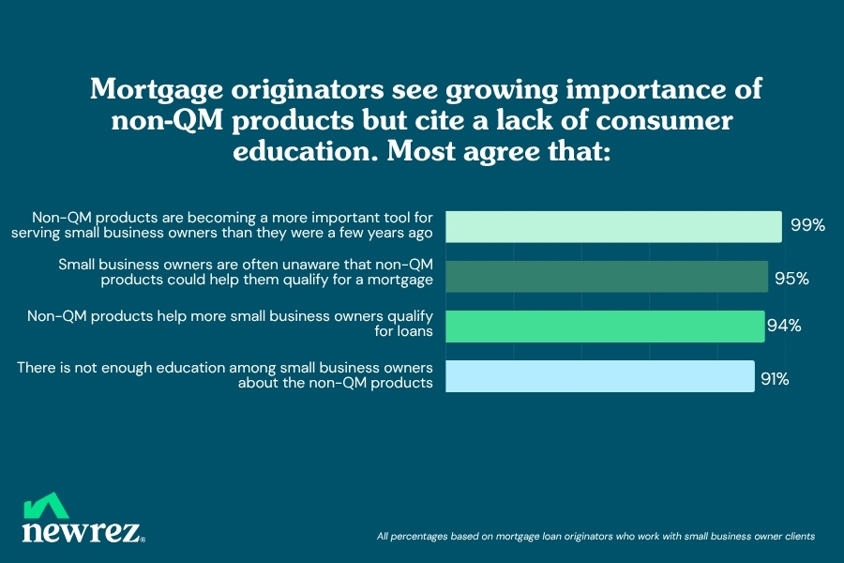
Originators working with these clients also reported a growing need for non-QM products:
- 99% said non-QM products are becoming a more important tool for serving small business owners than they were a few years ago.
- 94% said non-QM products help more small business owners qualify for loans.
Lack of awareness comes up again as an issue. 95% said small business owners are often unaware that non-QM products could help them qualify, and 91% said there isn’t enough education about these products.
Interest-Only Financing Can Help with Cash-Flow Needs
Income qualification isn't the only factor mortgage professionals identified. 71% of originators working with small business owners said interest-only loan options can help these clients better manage cash flow. But 82% said small business owners are often unaware of interest-only options.
For eligible borrowers focused on cash flow, interest-only is worth raising alongside fully amortizing loans. Interest-only loans work differently, though, and borrowers should understand when principal payments begin and how payments may change over the life of the loan.
Start the Conversation Earlier
Originators are already serving self-employed borrowers with both conventional and non-QM loans. There's still an awareness gap, but brokers can help close it by explaining how income qualification, documentation and loan options work early in the process. If you have questions about which Newrez products are available, or what might fit your clients’ needs, reach out to your Newrez account executive.
Methodology
Newrez surveyed mortgage loan originators, including Newrez broker partners and joint venture loan officers, between Sept. 25 and Oct. 7, 2026. A total of 99 originators responded, including 72 broker partners and 27 joint venture loan officers, with 96 indicating they work with small business owners who use business income to qualify. Percentages may not total 100% because respondents could select multiple answers for certain questions.